
Won and Asian FX: KRW, TWD, INR and ASEAN Currencies — 2026-09-27
Rising US Treasury yields and a firmer dollar pushed Asian FX to diverge this week: the rupiah posted its biggest weekly fall since May at 17,916/USD, while the won rallied into the Chuseok holiday on exporter dollar selling. The rupee recovered to 95.75 on Friday after dipping to 95.99 mid-week, with RBI intervention suspected. Bank Indonesia intensified intervention across NDF, spot and SBN markets.
Won and Asian FX: KRW, TWD, INR and ASEAN Currencies — 2026-09-27
Top developments
Rupiah suffers biggest weekly fall since late May
On Friday, September 25, Reuters reported the rupiah was set for its biggest weekly fall since late May, pressured by rising US Treasury yields, a stronger dollar and expectations around US policy. The rupiah closed sharply weaker at Rp17,916 per dollar on September 24, down 0.55% in a single day. The move matters for the wider EM-Asia complex — it reinforces the dollar-long bias already flagged by NDF positioning surveys and keeps Bank Indonesia under pressure to smooth the spot and DNDF markets.
Bank Indonesia intensifies FX intervention
With the rupiah at Rp17,916, Bank Indonesia said it was stepping up intervention across NDF, DNDF, spot, and secondary-market SBN (government bond) purchases to defend the currency, citing external pressure, US monetary tightening expectations and global inflation worries. Indonesian media stressed BI's readiness to "guard the FX market" against geopolitical conflict spillover. This is the week's most explicit central-bank smoothing signal in ASEAN and is likely to cap short-term rupiah NDF moves.
Won steadies into Chuseok on exporter dollar selling
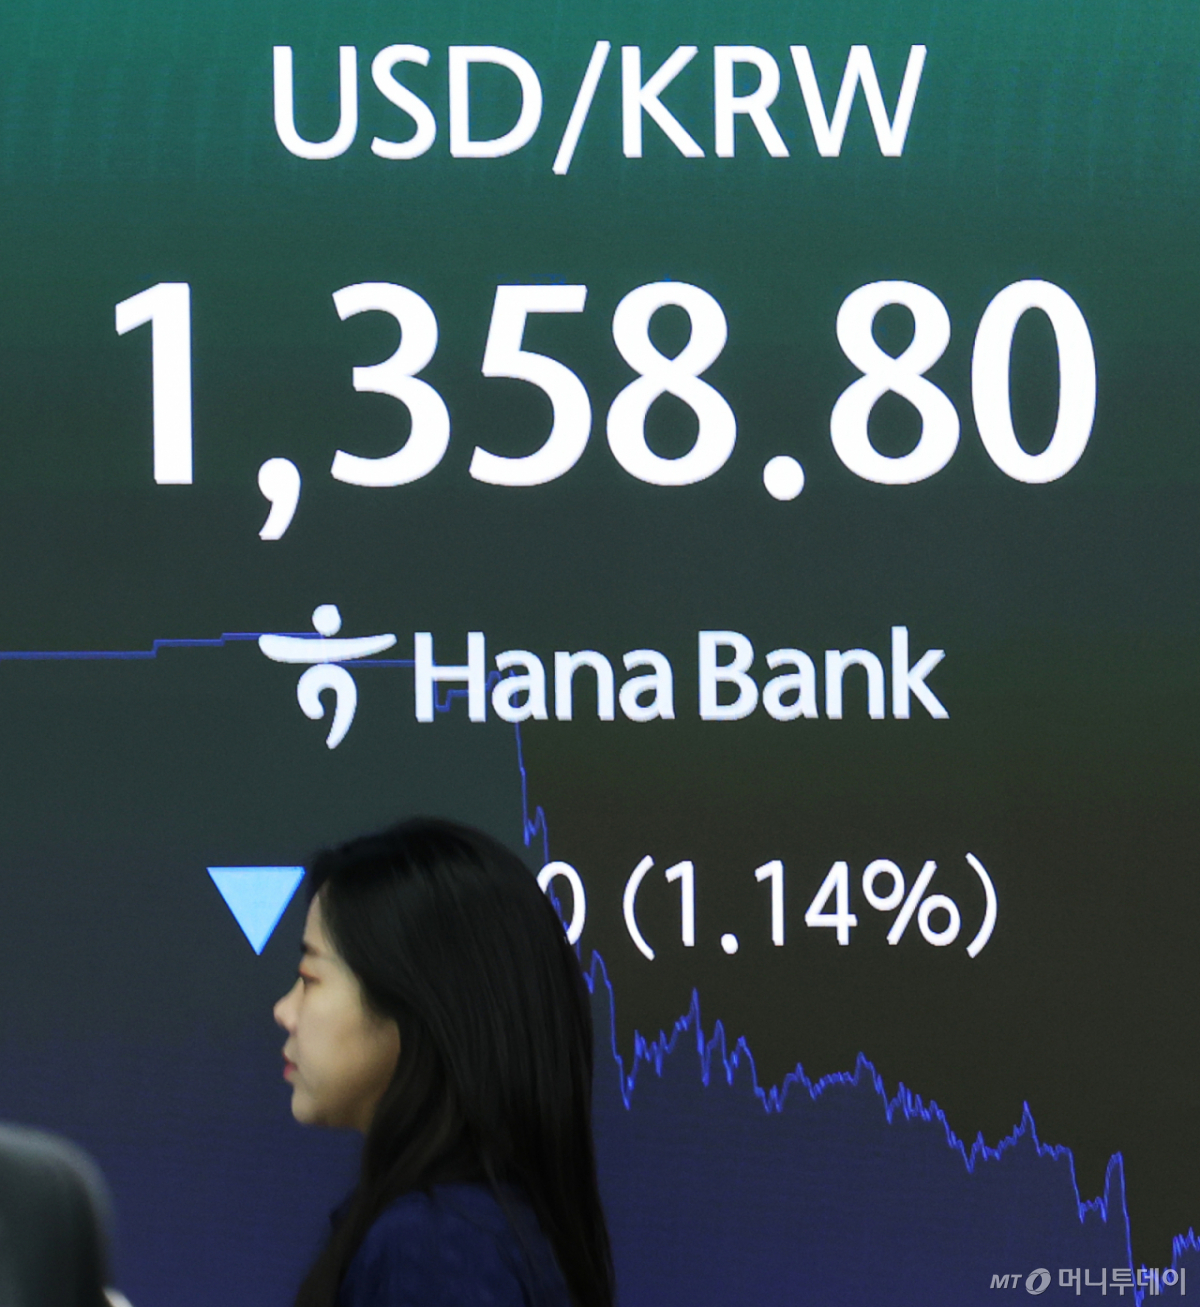
The won, which had brushed an intraday high of 1,387.9 per dollar on September 21, reversed direction as pre-Chuseok exporter nego (dollar-selling) flows and foreign buying of Korean equities kicked in, pushing the rate back into the 1,350s area. Money Today reports the rate fell to the 1,350 won band as exporter conversion supply piled up despite higher US yields and oil-driven dollar strength. For USD/KRW watchers, the post-holiday path now hinges on dollar-yen direction and the size of remaining nego orders.
Rupee swings, but holds below 96 with RBI suspected in the market
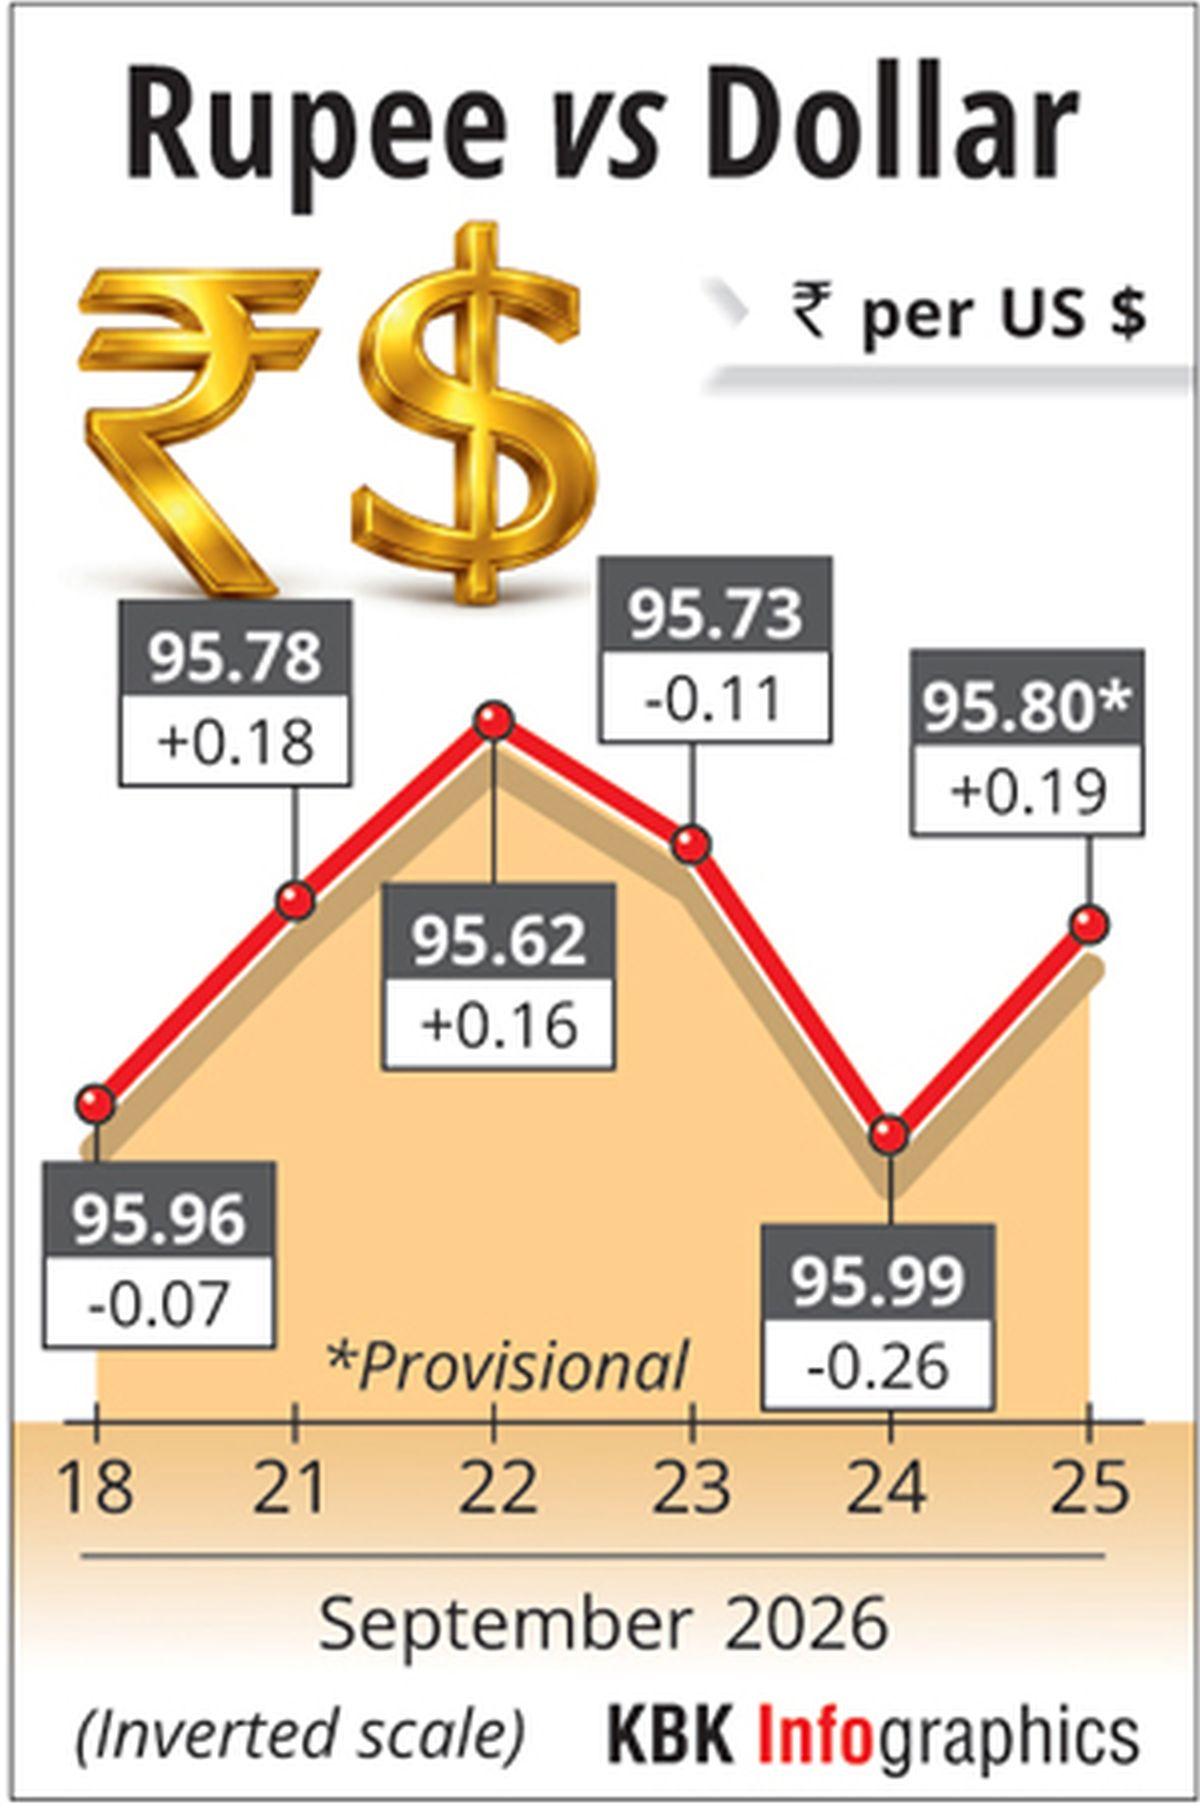
The rupee closed at 95.75 on Friday, September 25, appreciating 24 paise on improved global risk sentiment and possible RBI intervention; traders noted it held above the 96-mark. Mid-week it had slid 26 paise to 95.99 (September 24) on firmer crude and stronger dollar, with the 10-year Indian benchmark yield hitting 7.11%, its highest since May 21. The week's pattern — sharp dips bought near 96 — is a classic RBI-smoothing footprint that NDF desks watch closely for forward-point cues.
Local view
Korean-language media frame the rate turn as a "nego vs. dollar" contest. Money Today asks whether USD/KRW can break the ₩1,363 resistance as exporter dollar selling boosts KRW liquidity, noting the rate had come close to 50 won of gains before exporters' nego volume and foreign stock inflows turned it around.
Indonesian outlets uniformly credit BI's intervention toolkit. Bisnis Indonesia reported BI actively "monitoring and guarding" the FX market against geopolitical conflict pressure and domestic dollar demand, while Suara.com attributed the weakness to rising US monetary tightening expectations and fiscal uncertainty.
Hindi-language coverage is comparatively upbeat: Bhaskar Hindi reported RBI Deputy Governor's view that the rupee — down a cumulative 13.1% point-to-point from March 31, 2025 to September 16, 2026 — has a "fair case to stabilise and appreciate," supported by the current account outlook and FTA opportunities. Whalesbook (Hindi) sees the rupee trading in a 94.5–96 range under RBI management.
Context & numbers
- USD/IDR: Rp17,916 close (Sept 24, –0.55%); Rp17,914 quoted Sept 27; Rp17,917 quoted Sept 26.
- USD/INR: 95.75 Friday close (Sept 25, +24 paise); intraweek low 95.99.
- USD/KRW: intraday high 1,387.9 on Sept 21, back into the 1,350s within days.
- India 10-year yield: 7.11% (+6 bp), highest since May 21.
- BI cut-off rate debated around a hold at 5.75% ahead of the September RDG decision, with markets watching the rate call closely.
On the radar
- Post-Chuseok USD/KRW direction: Korean media flag the dollar-yen path, remaining exporter nego volume and possible Japanese FX-authority intervention as the key variables for the won after the holiday.
- BI's September rate-decision aftermath: how much the central bank leans off intervention-heavy defense toward rate policy.
- Rupee trajectory: local forecasts cluster in the 94.5–96 band, contingent on crude oil and RBI's FCNR(B)-driven inflows being tested by rising oil prices.
- NDF positioning: the latest Reuters/Investing positioning poll showed dollar-long bias across nine Asian EM currencies including the won, rupiah, rupee, peso and baht — watch whether Friday's risk-sentiment improvement unwinds those shorts.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
