
Korea Savings, Pensions and Tax-Break Accounts — 2026-10-29
South Korea announced a major mandate requiring all employers to externally fund retirement severance benefits by 2030, starting with large firms in 2028. Simultaneously, regulators are opening the 500 trillion won pension market to fund-type plans and culling underperforming default products to boost returns. Meanwhile, domestic deposit rates have risen to 3.45% as banks compete for deposits, while government guidance clarifies new tax deduction limits for year-end pension contributions.
Korea Savings, Pensions and Tax-Break Accounts — 2026-10-29
Top developments
Mandatory External Funding for Severance Benefits by 2030
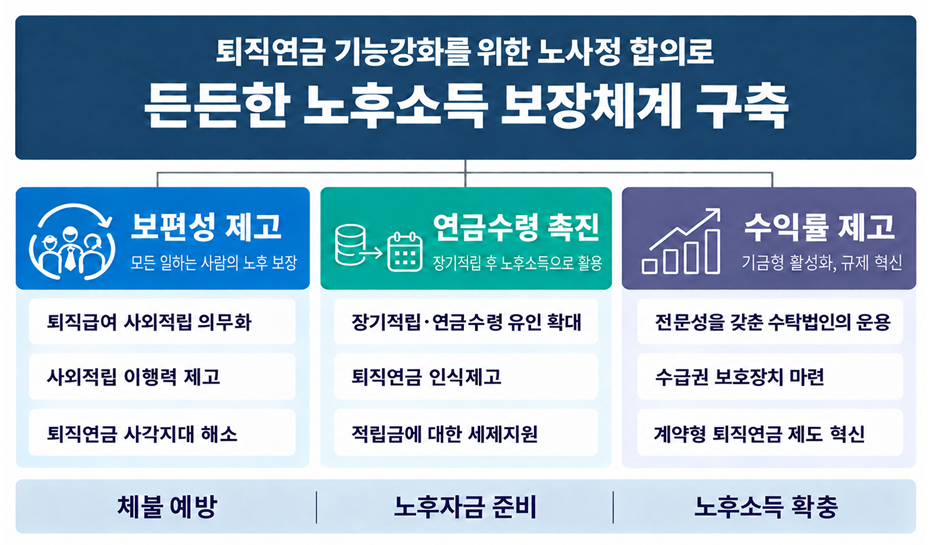
The South Korean government will mandate that all workplaces keep retirement benefits in external financial institutions by 2030, aiming to protect workers from employer insolvency risks. The rollout is phased, beginning in 2028 with companies employing 100 or more staff, and expanding to smaller firms thereafter. This structural change forces the accumulation of severance pay outside company balance sheets, significantly altering corporate liability management and boosting demand for asset management services.

Fund-Type Plans to Replace Low-Yield Default Options
In response to the retirement pension pool returning just 6.47% last year, authorities are introducing fund-type retirement pensions to the 501.4 trillion won market. The Financial Supervisory Service (FSS) is also moving to cull "default option" products that combine low returns with high fees, targeting the 13.6 trillion won currently sitting in underperforming funds. This shift aims to professionalize asset management within the pension sector and improve long-term yields for savers.
New Risk Grades for Pension ETFs
Starting in January 2027, the FSS will require retirement pension Exchange-Traded Funds (ETFs) to display clear risk grades and adhere to investment caps. This regulation comes as pension ETF holdings reach 99.8 trillion won, highlighting the need for greater transparency and risk management in retail-facing retirement products.
Deposit Rates Rise Amid Competitive Banking Landscape
Competition for deposits has intensified, with savings banks raising rates to match commercial banks. Some commercial bank time deposit products now offer rates exceeding 4%, prompting savings banks to follow suit to prevent capital outflow. The average interest rate on interest-bearing deposits rose to 3.45% per year in October, up 0.24 percentage points from the previous month.
Local view
Local media outlets like Seoul Economic Daily and Chosun Biz are focusing on the structural risks of the current pension system, noting that the 500 trillion won market has been constrained by low-return default options. Editorials emphasize that the success of the external funding mandate will depend on the expertise and independence of the financial institutions managing these new pooled assets.
Digital Times reports on the "reverse money movement," where savers are shifting funds to higher-yield products, forcing smaller savings banks to aggressively raise rates to compete with major commercial banks offering 4%+ yields.
Context & numbers
- Pension Pool Size: The domestic retirement pension market assets have surpassed 500 trillion won, with significant disparities in enrollment based on income and employment type.
- Deposit Rates: The average interest rate on interest-bearing deposits rose to 3.45% in October 2026. Pure savings deposit rates increased to 3.39%.
- Tax Deduction Limits: For year-end tax settlements, the tax credit limit for pension savings is 6 million won for pension savings alone, or 9 million won when combined with IRP (Individual Retirement Pension) contributions.
- ISA Limits: The government has confirmed that the current ISA (Individual Savings Account) contract period and annual contribution limits will be maintained, rejecting proposals to shorten terms or restrict carryovers.
On the radar
- Year-End Tax Filing Season: Savers are being advised to maximize pension and IRP contributions before year-end to secure the 9 million won combined tax deduction limit.
- ISA to Pension Conversion: Recent guides highlight additional tax credits of up to 3 million won for transferring ISA maturity funds into pension savings or IRP accounts, a key strategy for 2026 tax planning.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
