
Offices and Commercial Property Distress — 2026-09-25
This week's big story is Bloomberg's report that the US office crisis has moved decisively into the CMBS market, as high rates and maturing loans force investor losses. A Yardi Matrix office report flags loan maturities peaking in the years ahead, while Frankfurt continues its push to repurpose empty offices — including three schools moving into a giant office complex.
Offices and Commercial Property Distress — 2026-09-25
Top developments
US office crisis now hitting CMBS investors
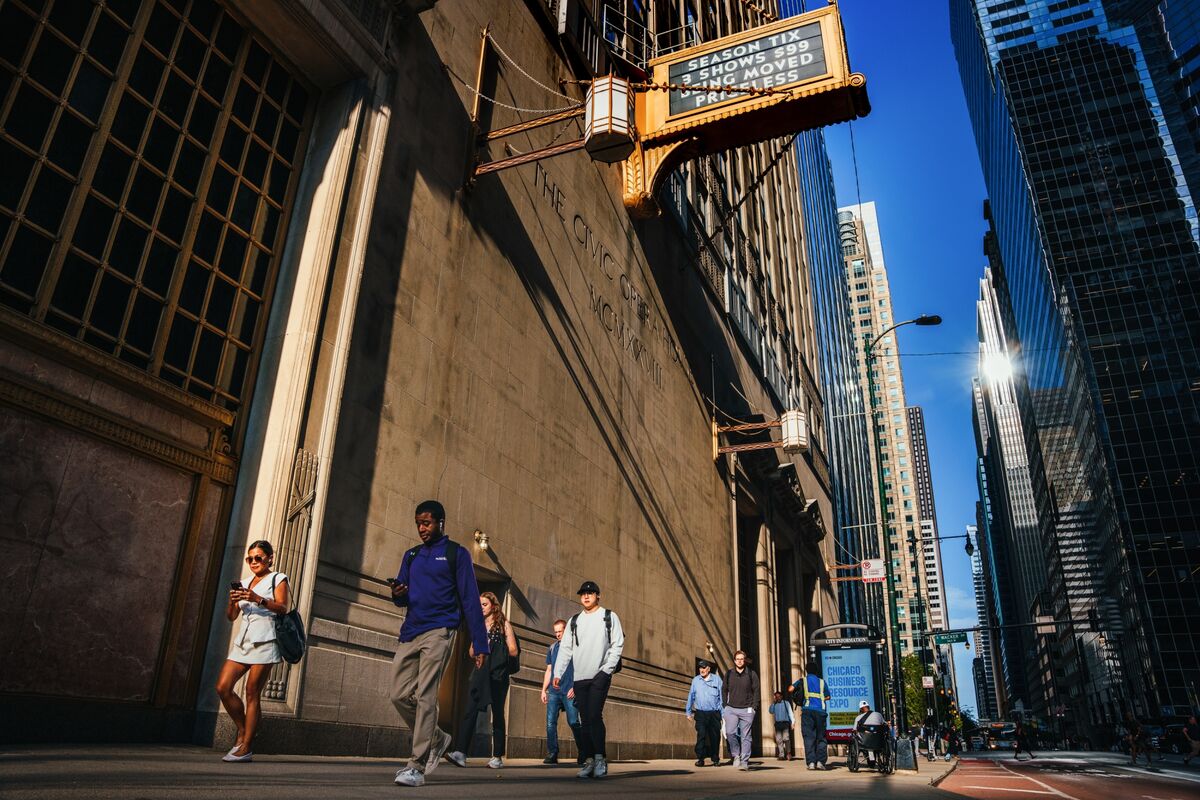
Bloomberg reported on September 21 that with interest rates staying high and billions of loans coming due, US cities and building owners are "finally having to contend with the crisis" — with losses now flowing through to CMBS investors. The piece underscores that the office repricing cycle is no longer deferrable at the lender level. This matters for tracking where realized lender losses will show up in 2026–2027 data.
Loan maturities add to market strain
A Yardi Matrix office report published September 22 via Commercial Property Executive warns the office sector faces another challenge: loan maturities are expected to peak in the coming years, compounding pressure from rates, low occupancy and refinancing难度. Expect elevated distress and workout activity as towers hit maturity walls.

Victor, N.Y. proposes eminent domain over troubled mall CMBS loan
In an unusual resolution tactic, the Rochester suburb of Victor, N.Y. proposed taking title to the Eastview Mall and Commons retail property via eminent domain to reset the mall's capital structure, Commercial Real Estate Direct reported on September 21. While retail rather than office, it signals how distressed CMBS workouts are being restructured at the local-government level.
Connecting the distress data: CMBS backdrop
Context for this week's news: the Trepp CMBS office delinquency rate hit an all-time high of 12.34% in January 2026, and just five US metro areas account for more than a third of all CMBS office delinquencies. CMBS delinquency volume was roughly flat in August at $47.42 billion.
Local view
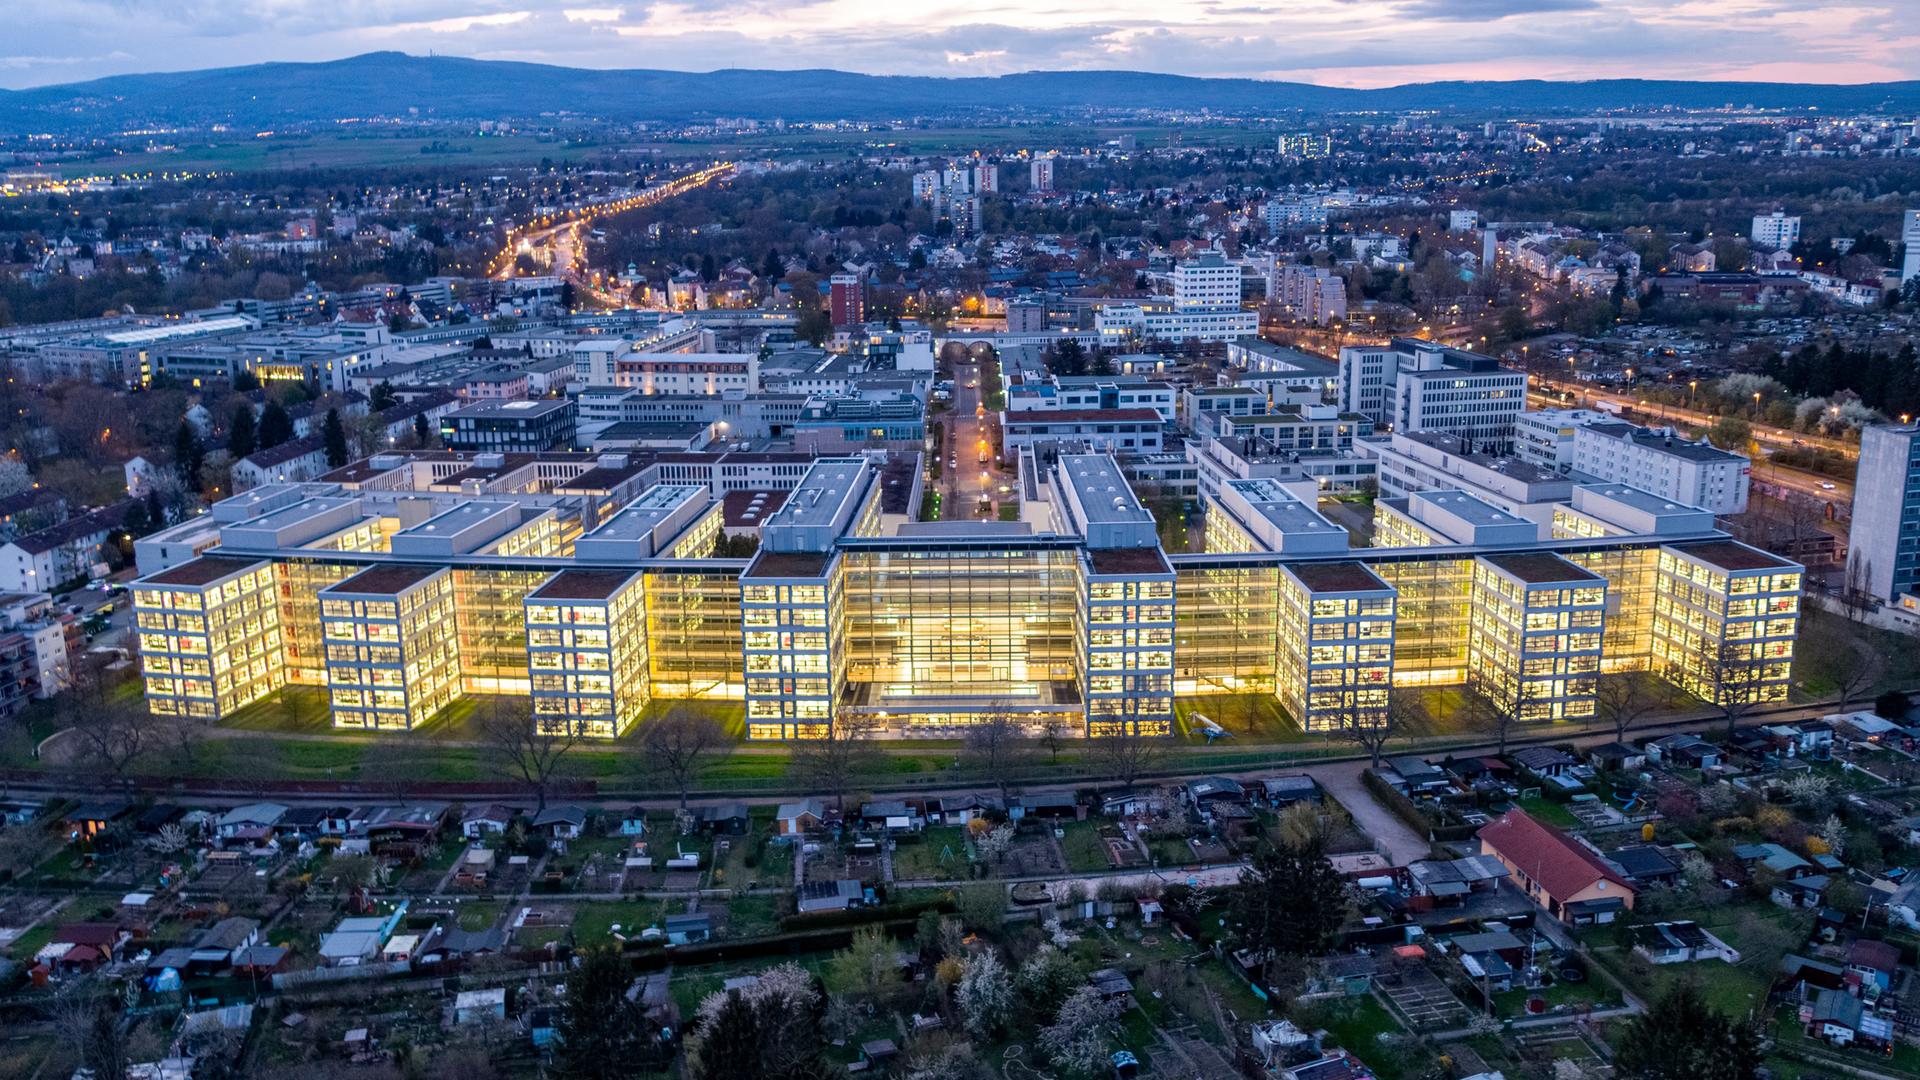
German media this week focused on repurposing rather than lender losses. Hessen's hessenschau (September 23) reported that three schools are moving into a massive Frankfurt office complex — the largest completed office-conversion project of its kind in the city — as Frankfurt grapples with a shortage of land for new school construction. Ad-hoc-news (September 23) adds that Frankfurt counts 4,600 empty apartments and plans its first conversion ordinance still in 2026, a year after the state law enabling it. DIE ZEIT (September 24) reports new tenant-protection rules against expensive housing in Hessen.
Context & numbers
- US office vacancy, per CBRE's latest quarterly reporting, was 18.6% overall and 12.7% prime, with net absorption of 38.9 million sq. ft over four quarters and leasing activity of 62.4 million sq. ft in Q2; Midtown Manhattan prime vacancy fell to just 2.9% — a flight-to-quality dynamic that keeps trophy towers leasing well.
- JLL reported total vacancy declining aggressively (60 bps QoQ) with 30+ million sq. ft of occupancy gains over twelve months as of July.
- The widening gap between leasing recovery and distress is where CMBS losses (see Bloomberg above) are landing.
On the radar
- Connect CRE's "Return to Lender" weekly roundups — the latest edition, dated September 24, is worth tracking for property-level defaults returning to lenders.
- Frankfurt's first Umnutzung (conversion) ordinance, reportedly still planned for passage before end-2026.
- Upcoming Trepp CMBS delinquency readings for September, to see whether office delinquency pushes past its January record of 12.34%.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
