
Offices and Commercial Property Distress — 2026-09-20
The U.S. office market shows a stark divergence: vacancy rates are falling in prime sectors due to AI-driven leasing booms, while distressed assets face rising CMBS delinquencies and a surge in adaptive reuse conversions. In Europe, regulatory hurdles continue to block the conversion of vacant offices into housing despite severe shortages, with Germany reporting a deficit of 1.4 million units.
Offices and Commercial Property Distress — 2026-09-20
Top developments
Manhattan’s "Return-to-Office" Paradox
Brokers report a "complete turnaround" in the Manhattan office market, where rents are soaring and availability is plummeting, driven largely by AI companies doubling or tripling their lease spaces. This contrasts sharply with the broader narrative of distress; while general vacancy may remain high in older stock, trophy towers and tech-heavy submarkets are experiencing a leasing frenzy that defies earlier predictions of permanent remote-work erosion.

CMBS Delinquency Volume Stabilizes at High Levels
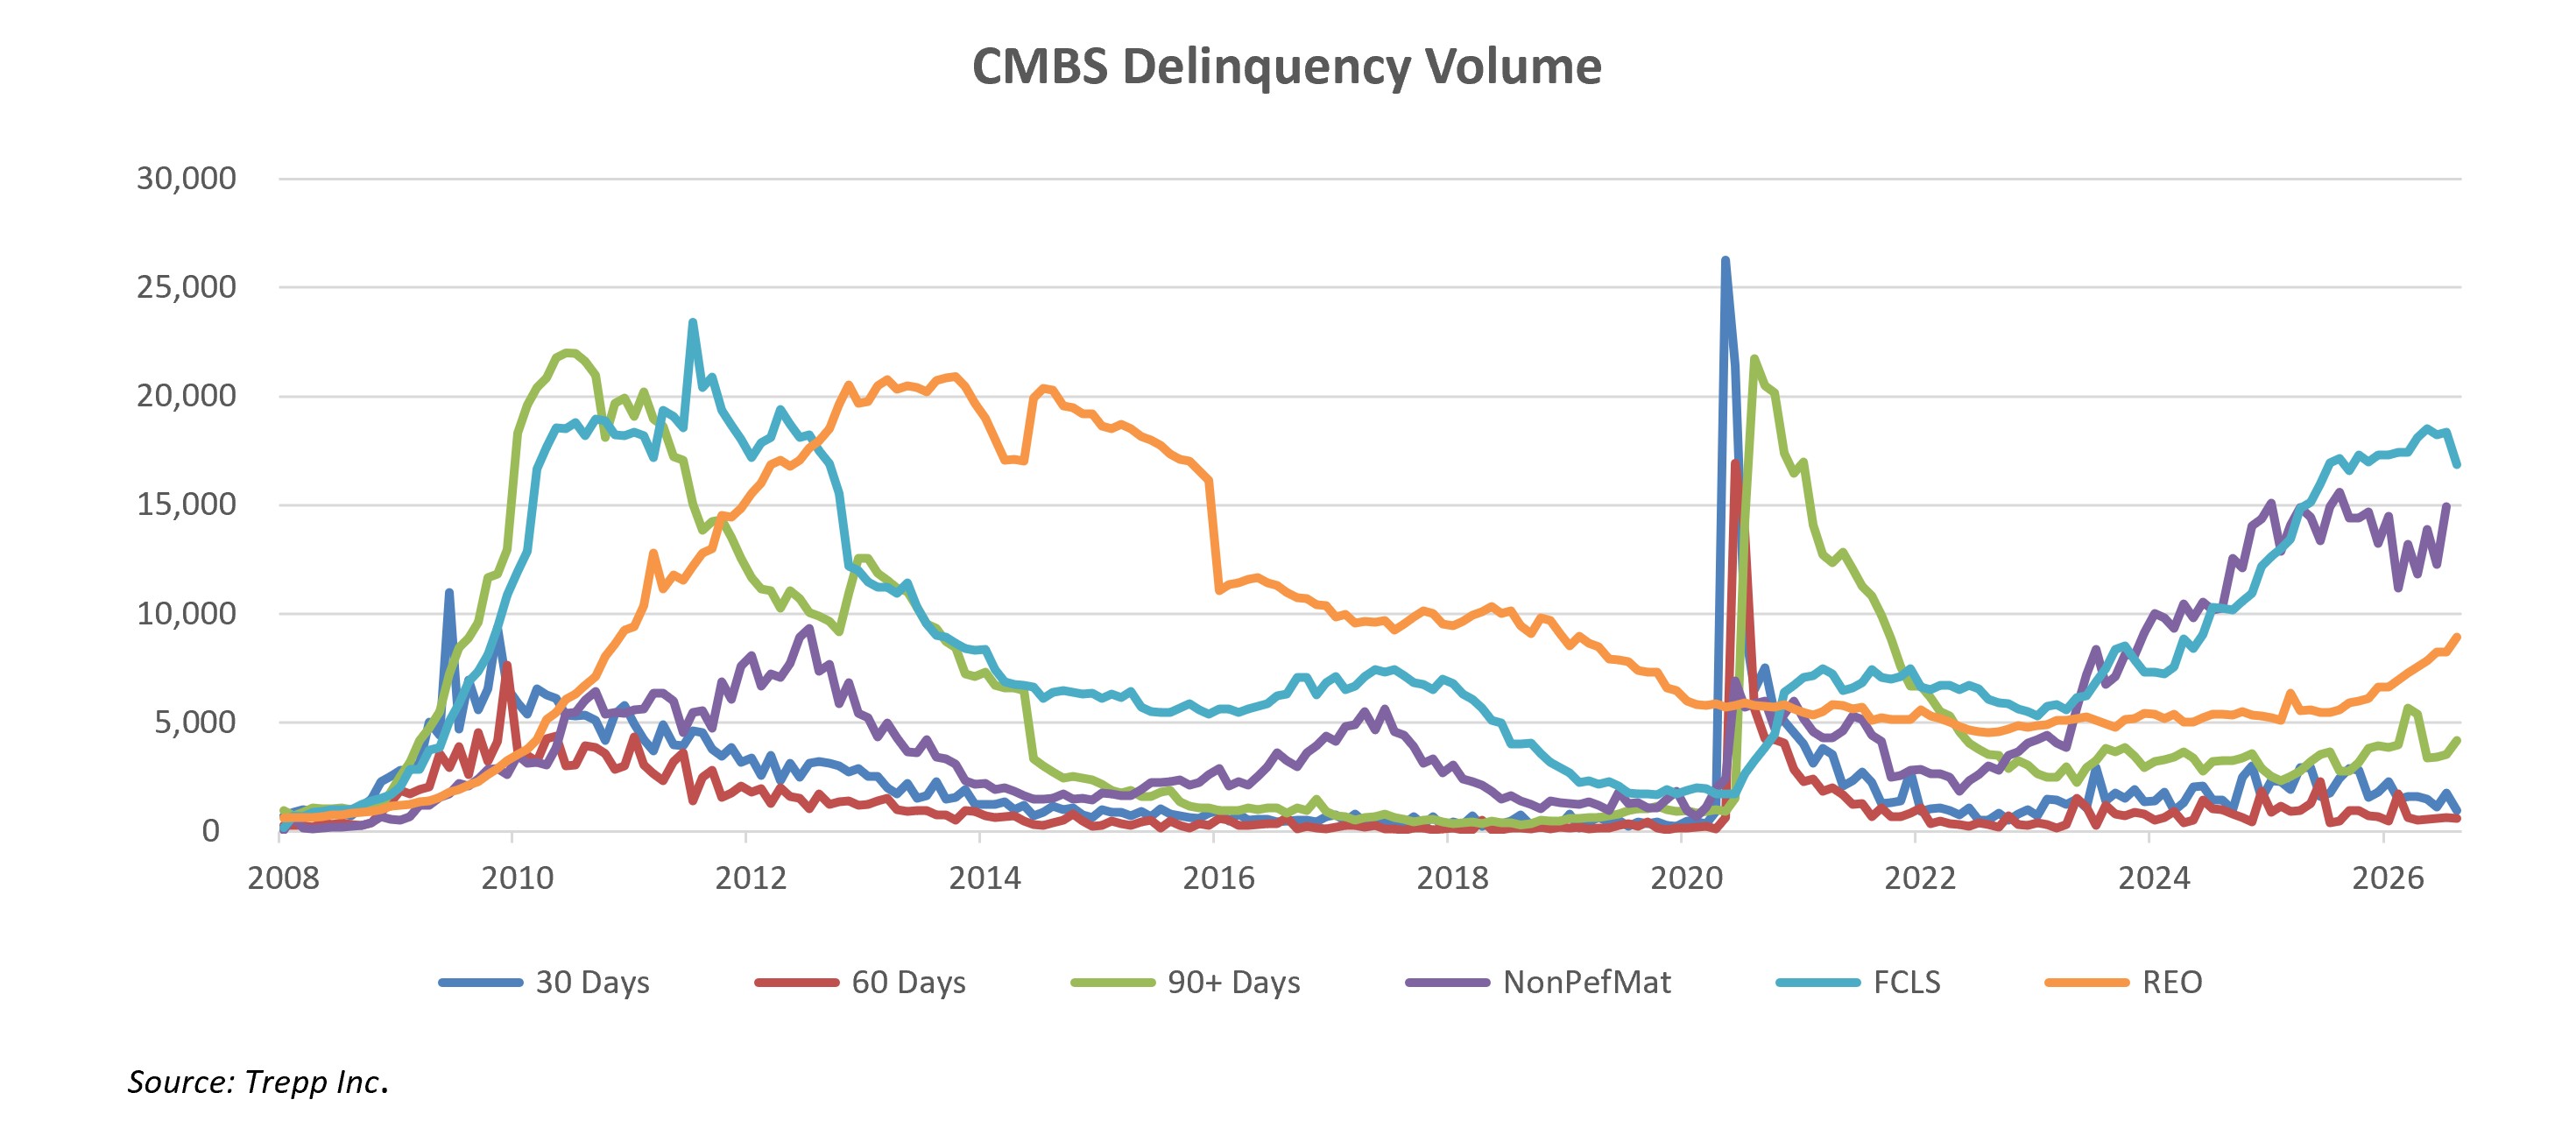
The volume of CMBS loans more than 30 days delinquent remained relatively flat in August 2026 at $47.42 billion, decreasing only slightly by $72 million from the previous month. While this stability might suggest a pause in new defaults, it reflects a market where lenders have already recognized losses or moved assets to special servicing, leaving the remaining pool of distressed debt largely unchanged as the "extend and pretend" era reaches its limits.
Office-to-Campus Conversions Gain Momentum
Universities are increasingly pursuing office-to-campus conversions as a viable exit strategy for obsolete office buildings, repurposing them into urban campuses. This trend offers an alternative to residential conversions, which often face zoning and structural challenges, by leveraging the institutional demand for flexible educational and research spaces in city centers.

AI Expansion Drives Global Office Rents
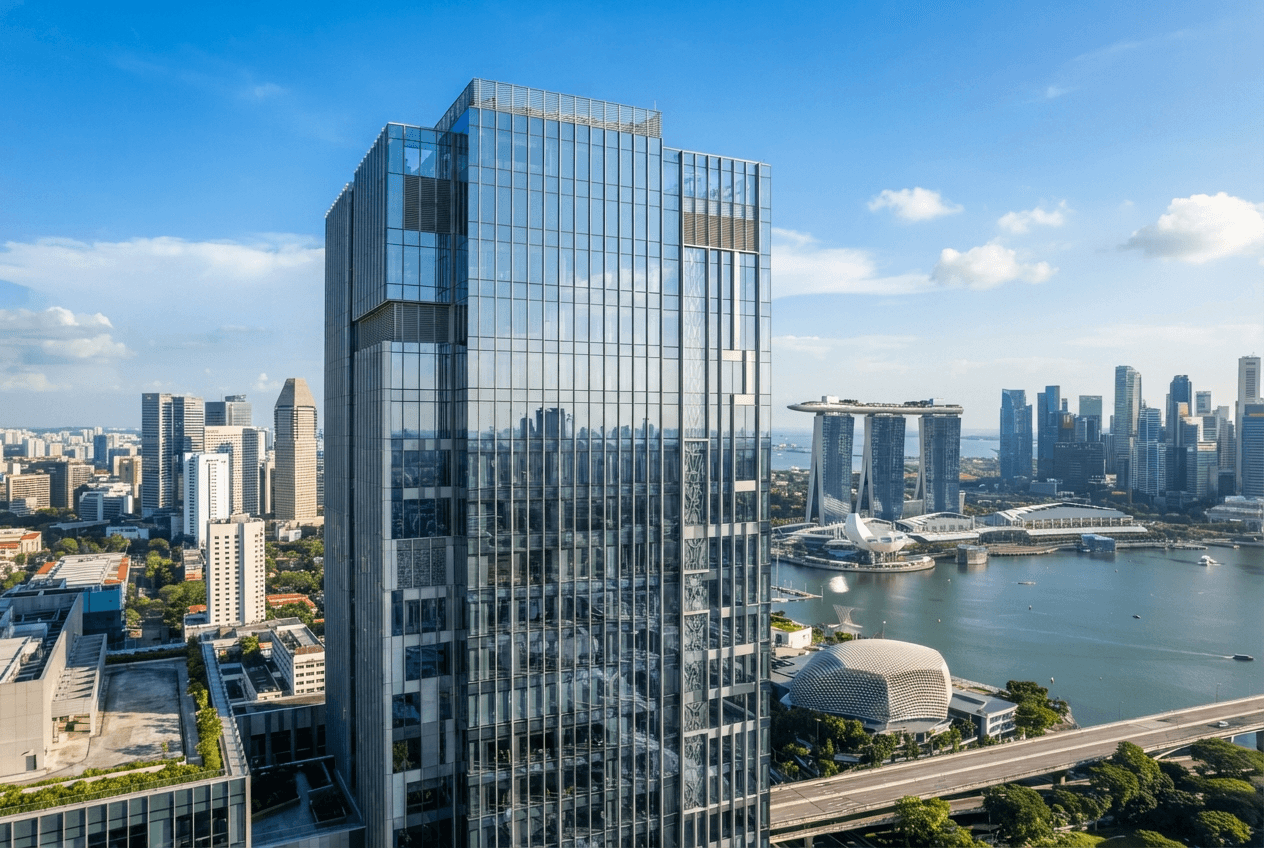
In Singapore and other global hubs, the expansion of AI firms like OpenAI and Anthropic is pushing office rents up by as much as 10%, signaling that the "flight to quality" is now a "flight to AI-capable infrastructure." This demand is creating pockets of extreme tightness even in markets previously considered oversupplied, complicating the distress narrative for well-located Class A properties.
Local view
Germany: Regulatory Gridlock Blocks Housing Solutions
German media reports highlight a critical disconnect between the severe housing shortage (estimated at 1.4 million units) and the regulatory framework blocking office-to-housing conversions. Börse Express notes that building law and noise protection regulations are actively hindering the repurposing of vacant commercial areas, forcing municipalities like Munich and Wörthsee to test alternative, less efficient solutions.
SoCal: Sector Divergence
The Los Angeles Times notes that Southern California’s commercial real estate is moving in divergent directions, with industrial and multifamily sectors showing strength while office remains under pressure. This regional split underscores that "distress" is not uniform, even within major metropolitan areas, as location-specific factors drive vastly different outcomes for property owners.


Context & numbers
- Vacancy Rates: U.S. office vacancy fell 10 bps to 18.6% in Q1 2026, with prime vacancy dropping 80 bps to 12.7%; Midtown Manhattan prime vacancy is just 2.9%.
- Absorption: Class A net absorption totaled +4.4 million sq ft recently, with over 30 million sq ft of occupancy gains in the past 12 months.
- CMBS Delinquency: The overall CMBS delinquency rate was reported at 7.55% in March 2026, up 41 bps from February, while office-specific delinquencies hit historical highs earlier in the year.
- Conversions: Office-to-residential conversions reached 90,300 units in 2026, a 28% year-over-year increase, driven by $300 billion in maturing office loans.
On the radar
- Q3 Broker Reports: Major brokers (CBRE, JLL, Cushman & Wakefield) are expected to release Q3 2026 data soon, which will clarify if the Q1/Q2 absorption momentum held through the summer.
- Maturity Wall Pressure: With $300B in maturing office loans cited as a driver for conversions, watch for increased distressed sales activity in Q4 as refinancing options dry up for non-prime assets.
- RTO Mandate Fatigue: Recent analyses suggest remote work remains stable despite mandates, with "loyalty test" narratives fading; monitor if this leads to further space rationalization or stabilization in suburban markets.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
