
Offices and Commercial Property Distress — 2026-10-27
The U.S. office market shows diverging trends: while Seattle and Wilmington report leasing recoveries, CMBS delinquency rates have spiked to 12.2%, exceeding financial crisis peaks. Meanwhile, India’s office leasing hit a nine-month record, driven by Global Capability Centers, though record supply is pressuring vacancy rates.
Offices and Commercial Property Distress — 2026-10-27
Top developments
Seattle sees first occupancy gain since 2021
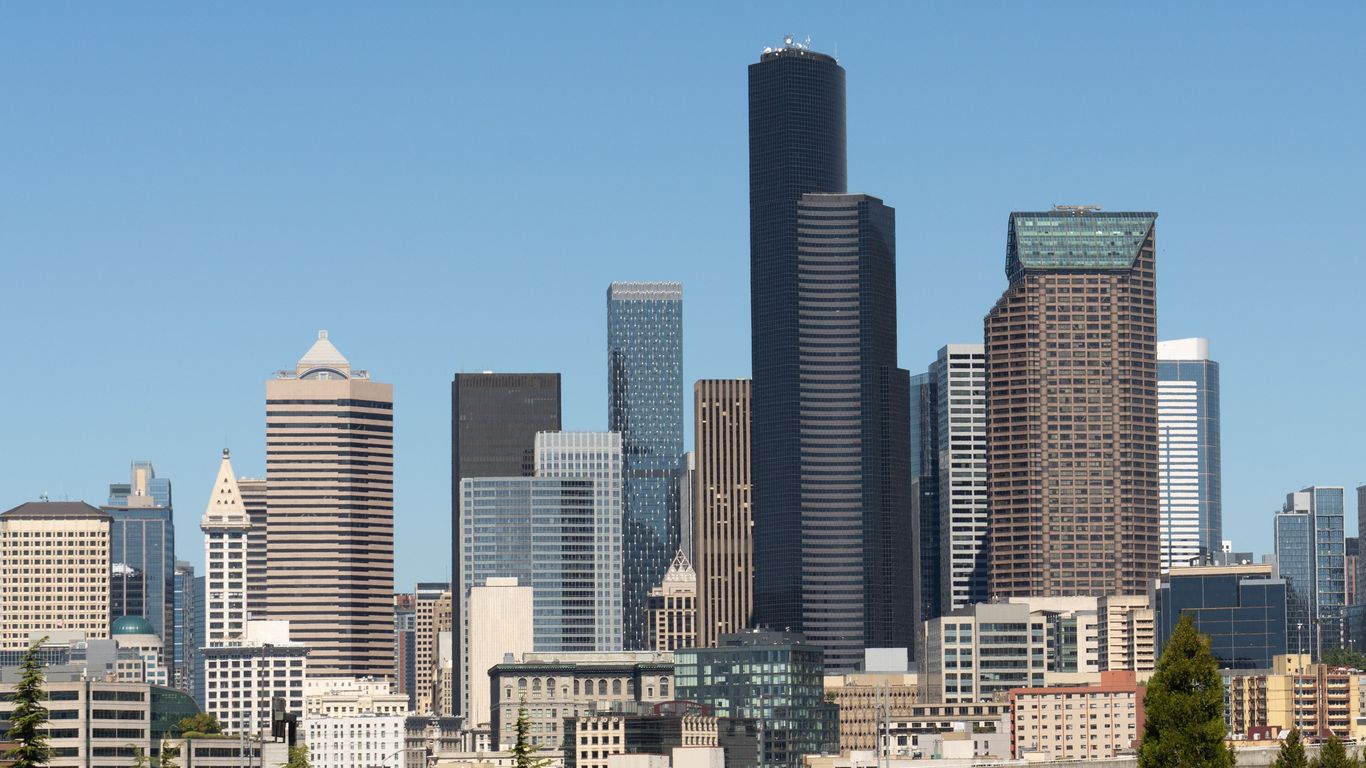
Downtown Seattle gained occupied office space for the first time since 2021, marking a potential turning point for the tech-heavy market. Despite this recovery, vacancy rates remain stubbornly high above 35%, indicating that while leasing demand is returning, the market is still far from pre-pandemic stability.
CMBS delinquency spikes to 12.2%
Office commercial mortgage-backed securities (CMBS) delinquency rates have re-spiked to 12.2%, a level significantly worse than the peak during the 2008 financial crisis. This surge signals that the "extend and pretend" strategy used by lenders is collapsing, forcing owners to recognize losses as building values are repriced sharply downward.

India’s office leasing hits record high
India’s office market recorded its highest leasing activity for a January-September period, reaching 61.06 million square feet. Global Capability Centers (GCCs) accounted for 43% of this demand, with Bengaluru leading the surge. However, record completions of new supply are pushing vacancy rates marginally higher, testing developer returns.

Wilmington vacancy falls to 20-year low
After six years of distress, the office market in Wilmington, Delaware, has rebounded with vacancy rates falling to their lowest level in two decades. This unexpected stability highlights how secondary markets with lower supply pressure are recovering faster than major metropolitan hubs struggling with excess inventory.
Local view
While no specific local-language media outlets from the past week were provided in the research results for this signal, national data indicates significant divergence. In Chicago, DekaBank recently provided $79 million in financing for a Sterling Bay office building in Fulton Market, allowing the owner to pay off a construction loan. This suggests that while distressed assets are struggling, prime locations in secondary markets are still attracting institutional capital.
Context & numbers
- CMBS Payoff Rates: Only 57.98% of CMBS loans reaching final maturity in September were paid off on time, down from August’s 51.45% but below the 59.84% trailing 12-month average.
- Office Occupancy: Kastle Systems badge data shows office occupancy has hit post-pandemic highs, but this activity is concentrated heavily on Tuesdays through Thursdays, reshaping commuting patterns.
- Lender Portfolio Growth: Despite elevated interest rates, most lender types posted modest growth in outstanding CRE loan balances in Q2, with banks and insurance companies driving most of the expansion.
On the radar
- Debt Maturity Wall: A "massive" wall of commercial real estate debt is coming due over the next two years, presenting significant opportunities for distressed debt investors and potential defaults for overleveraged owners.
- Conversion Pipeline: The U.S. office-to-residential conversion pipeline continues to grow, with cities like Washington, D.C. and Boston offering significant tax abatements to accelerate the creation of new housing units from vacant office space.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
