
Startup Funding Tracker — 2026-09-19
Capital deployment slowed this week compared to recent megadeals, with confirmed funding concentrated in AI infrastructure, fintech, and physical tech. Temporal leads confirmed rounds at $550M for AI infrastructure, while FinTech saw over $850M raised across multiple deals. No major IPO filings or exits announced in the last 24 hours.
Startup Funding Tracker — 2026-09-19

Top Confirmed Rounds
| Company | Stage | Amount | Lead Investor | Sector | HQ |
|---|---|---|---|---|---|
| Temporal | Series B+ | $550M | — | AI Infrastructure | — |
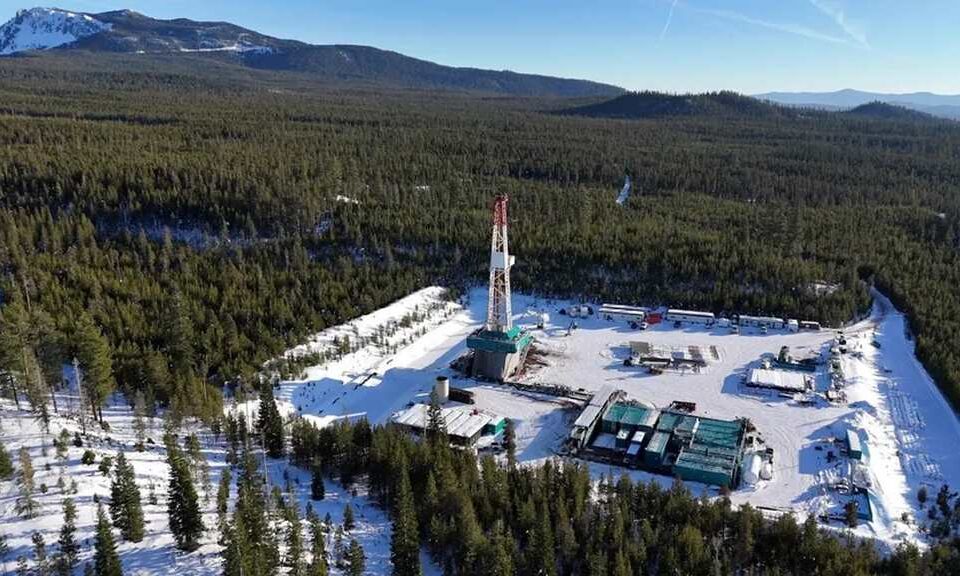
| Mazama Energy | — | Undisclosed | Andreessen Horowitz, Insight Partners | Energy / Infrastructure | — |
| Upscale AI | Seed | $100M | Maverick Silicon, Mayfield | AI Infrastructure | — |
| Multiple FinTech | Various | $850M+ (aggregate) | — | FinTech | — |
Deal Spotlights
Temporal — $550M Series B+
- Investors: Undisclosed lead; established infrastructure investors
- Use of proceeds: Temporal is scaling AI infrastructure to support enterprise AI deployment at scale. The company serves as a critical bottleneck layer for reliable, stateful AI workloads.
- Why it matters: This is the week's largest single-company raise, signaling investor appetite for infrastructure—not just frontier models. The funding demonstrates that capital is moving decisively away from pure LLM plays toward the operational backbone required for AI at scale.
- Valuation: Undisclosed
Upscale AI — $100M Seed
- Investors: Maverick Silicon, Mayfield (co-leads); StepStone Group, Stanford University, Qualcomm Ventures (participants)
- Use of proceeds: Upscale AI develops semiconductor and compute optimization solutions. Funding supports R&D and go-to-market for AI chip scaling.
- Why it matters: A $100M seed round is exceptionally rare and signals extreme confidence in the AI compute shortage thesis. The presence of Qualcomm and StepStone (infrastructure fund) shows institutional belief that compute scarcity will persist, justifying high early valuations.
- Valuation: Undisclosed
FinTech Sector — $850M+ Aggregate Week
- Investors: Multiple
- Use of proceeds: Spread across payments, lending, investment platforms, and financial infrastructure.
- Why it matters: FinTech's $850M+ weekly aggregate signals sustained capital availability in regulated tech despite broader macro uncertainty. The diversity of rounds (not concentrated in a single mega-deal) suggests healthy mid-market appetite.
- Valuation: Various
Sector Snapshot
-
AI Infrastructure & Compute: Temporal ($550M) and Upscale AI ($100M) lead a shift away from frontier model funding toward the systems, chips, and orchestration layers that enable AI deployment. Infrastructure plays are outpacing pure software LLM startups in announced capital this week.
-
FinTech: Over $850M raised across the week in payments, lending, and investment platforms, suggesting sustained institutional confidence despite macro headwinds and regulatory scrutiny.
-
Energy & Climate Infrastructure: Mazama Energy and related infrastructure plays continue to attract top-tier VCs (Andreessen Horowitz, Insight Partners), reflecting a multi-year pivot toward "physical tech" and energy-adjacent AI applications.
IPO & M&A Watch
No new S-1 filings, IPO pricings, or major M&A closures confirmed in the last 24 hours. Historical context: SpaceX filed its S-1 prospectus in May 2026 and chose Nasdaq as its listing venue. No comparable public-market exits announced this reporting period.
Notable Rumors (Unconfirmed)
No unconfirmed "in talks" deals with sufficient named reporting outlets identified in the past 24 hours.
What to Watch Next
- Upscale AI follow-on rounds: With a $100M seed, the company will likely be in Series A conversations within 12 months; watch for enterprise AI customers and deployment metrics.
- AI Infrastructure consolidation: As multiple infrastructure startups scale (Temporal, others), M&A interest from cloud and enterprise vendors (AWS, Azure, Google Cloud) may accelerate.
- FinTech Series B/C activity: Mid-market FinTech rounds above $50M should resume in Q4 2026 if macro conditions stabilize; regulatory tailwinds (open banking) could unlock new funding windows.
Reader Action Items
- For founders: Infrastructure + compute + regulated domains (fintech, energy) are attracting the most institutional capital right now. Frontier AI model pitches face higher skepticism; focus on solving operational bottlenecks or enabling enterprise AI deployment.
- For investors: Temporal's $550M round suggests Series B+ rounds in AI infrastructure can command nine-figure checks at scale. Seed rounds like Upscale AI's $100M are outliers; deploy barbell strategies (many smaller seeds + concentrated conviction bets on compute/energy infrastructure).
- For operators: Hiring signals: Temporal and Upscale AI are both scaling; watch their job postings for sales, product, and platform engineering roles—a strong indicator of near-term go-to-market focus.
Scope: Only deals CLOSED or formally ANNOUNCED in the past 24 hours (after 2026-09-17). Rumor-stage and retrospective summaries excluded from main table.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
