
Supply Chain Watch — 2026-10-02
Asian port congestion threatens to bleed into 2027 as typhoon backlogs and record China cargo volumes strain shipping capacity. Simultaneously, a new FreightWaves State of the Industry Report reveals volatility as the permanent reality for supply chain operators, while warehouse automation and AI logistics tools shift from pilots to operational infrastructure across the industry.
Supply Chain Watch — 2026-10-02
Top Stories
Asia's Port Congestion Crisis Extends Timeline Into 2027
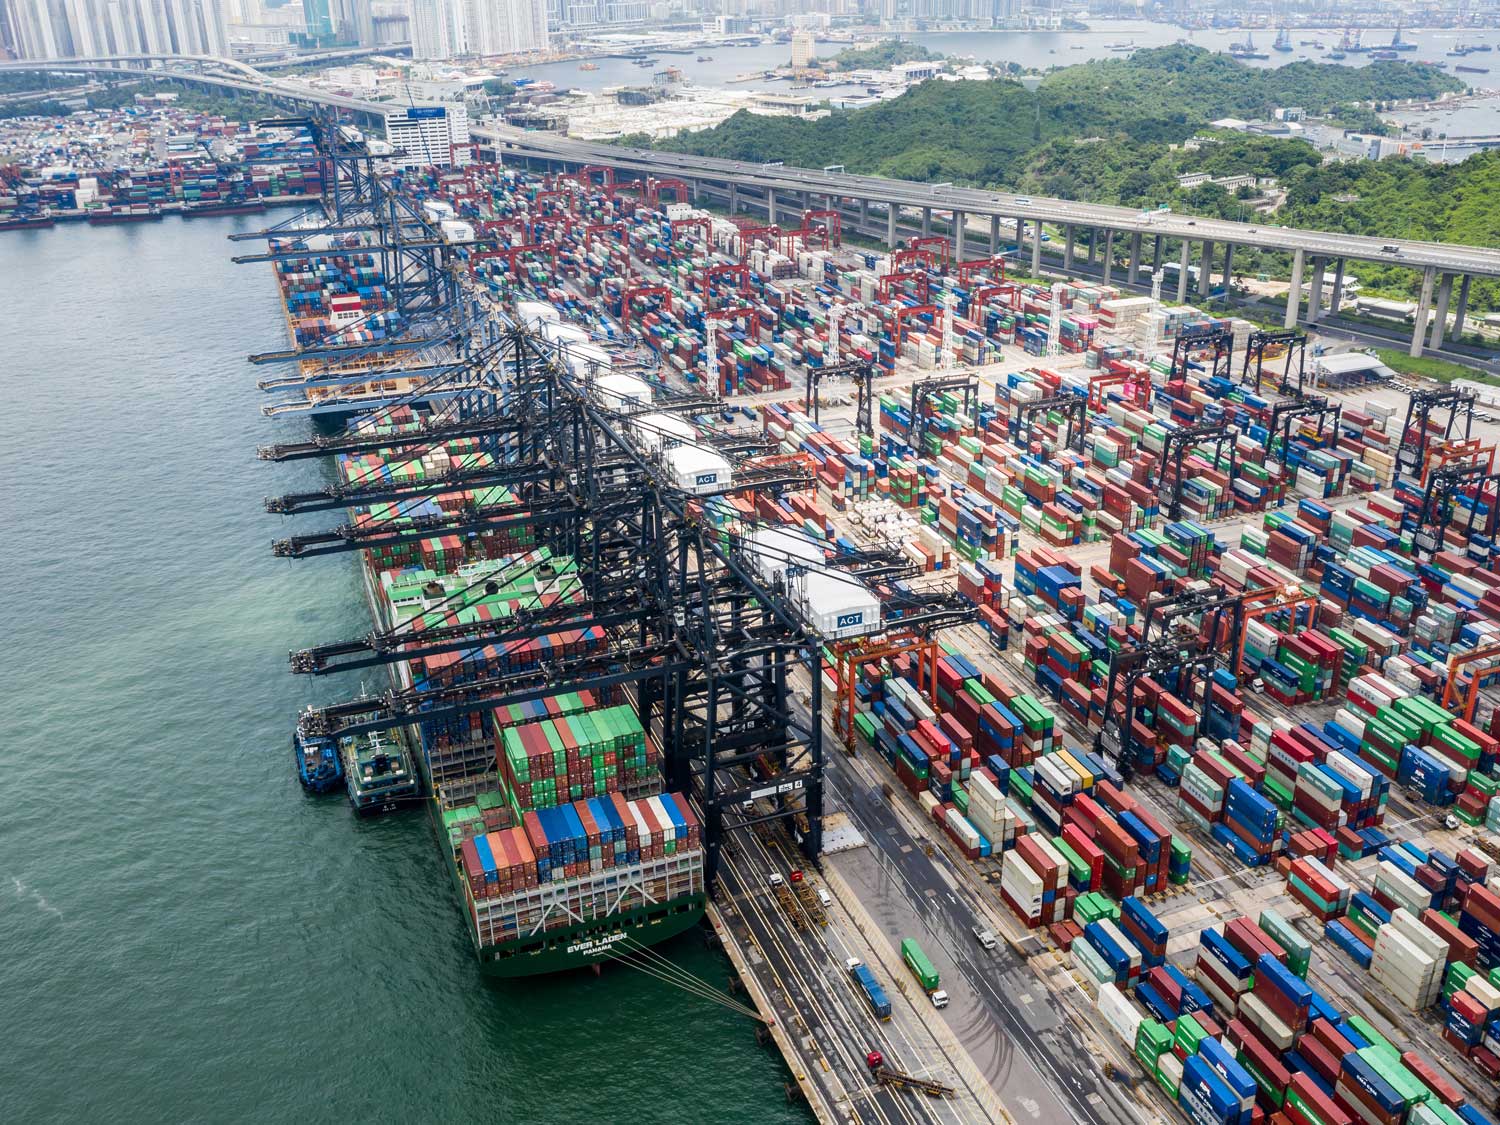
Port congestion in Asia that peaked this summer could persist for up to 10 months, potentially disrupting supply chains into summer 2027. Record China container volumes, typhoon-induced backlogs, and reduced sailing capacity during Golden Week are straining global shipping infrastructure. Multiple analysts warn that the congestion is no longer a cyclical peak season issue but reflects structural capacity constraints.
FreightWaves October 2026 State of the Industry Report: Volatility Now the New Normal
The latest State of the Industry Report from FreightWaves, released on October 1, 2026, identifies volatility as a structural—not cyclical—feature of supply chains in 2026. The report emphasizes that shippers must prioritize contract flexibility and scenario planning over attempting to time volatile markets. Value is increasingly migrating from traditional brokerage margins toward higher-value services including customs, compliance, warehousing, and supply chain financing supported by technology-enabled solutions.
freightwaves.com
2026 State of Logistics Report: Volatility is the new normal - FreightWaves
2026 State of Logistics Report: Volatility is the new normal - FreightWaves
Global Supply Chain News and Updates | FreightWaves
Freight winners in 2026 will build for disruption, uShip CEO says - FreightWaves
Shipping's Record 2026 Built on Fragile Foundations Amid New Risks
While the shipping industry posted its third consecutive all-time high earnings—measured by Clarksons' ClarkSea Index in late September 2026—this performance remains vulnerable to persistent disruptions. The industry continues to face structural oversupply of container vessels, with new-build capacity entering the market in 2026 deepening supply-demand imbalances. Multiple chokepoints including the Red Sea, Strait of Hormuz, Panama Canal, and Black Sea provide only temporary rate support while constraining route alternatives.
Shipping & Freight
Red Sea Diversions Raise Freight Costs 15-25% as Suez Alternative Proves Costly
Vessels bypassing Red Sea disruptions via Africa's Cape of Good Hope face freight rates that sit 15-25% higher than traditional Suez Canal routing. The diversion adds approximately 90% of Asia-Europe container traffic to longer alternate routes. In contrast, US West Coast imports via the Pacific experience minimal disruption—only 0-2 day delays and 5-10% rate increases from capacity spillover effects.
Ocean Freight Remains Structurally Oversupplied Despite Rate Support from Disruptions
Ocean freight remains deeply oversupplied according to industry analysis, even as geopolitical and weather disruptions provide temporary support. Fleet growth has outpaced demand since 2025, with a wave of new-build container capacity entering service in 2026 further deepening the structural imbalance. While chokepoints at the Red Sea, Strait of Hormuz, Panama Canal, and Black Sea limit shipping alternatives and support rates temporarily, these constraints prevent operators from leveraging full network flexibility.
Resilient Flooring Makers Rethink Sourcing as Tariffs and Freight Costs Reshape Market
Resilient flooring manufacturers are restructuring sourcing and product strategies as tariffs, elevated freight costs, and shifting housing demand reshape the market landscape. Supply chain pressures in 2026 are forcing producers to reconsider both sourcing geography and inventory positioning, with freight cost volatility playing a key role in margin compression across the sector.
Logistics & Warehousing
AI and Warehouse Automation Move from Pilots to Operating Infrastructure in 2026
The year 2026 marked a critical inflection point where logistics technology—particularly AI and automation—transitioned from pilot programs to permanent operating infrastructure. Key trends include AI-powered supply chain visibility, warehouse robotics deployment at scale, and technology-enabled compliance and resilience solutions. Logistics operators now embed AI into freight status updates, document intake, carrier vetting, and invoice auditing as standard operational procedures.
Geekplus and LPP Logistics Deploy Intelligent Warehouse Automation at Retail Scale
Geekplus and LPP Logistics announced a partnership deploying intelligent warehouse automation to transform retail logistics operations. The partnership demonstrates how modular, replicable automation strategies help logistics providers build flexibility to adapt to seasonal demand, changing customer needs, and expansion requirements. This collaboration exemplifies how robotics and AI are moving beyond manual sorting into comprehensive warehouse transformation.
Technology & Innovation
AI Investment in Supply Chain Logistics Accelerates Rapidly in 2026
AI investment in logistics is accelerating at an unprecedented pace, with capital flowing toward automation of high-impact workflow tasks. Priority areas include autonomous status updates, intelligent document intake, carrier evaluation systems, and invoice automation with compliance verification. The convergence of lower AI model costs and higher labor expenses makes automation of routine logistics tasks increasingly profitable.
Warehouse Robots Transform Logistics Operations While Preserving Complex Labor Functions
Warehouse robots in 2026 increasingly specialize in specific, repeatable tasks rather than wholesale job replacement. Advanced robotic systems handle sorting, material handling, and repetitive picking operations, while human workers remain essential for exception handling, quality control, and complex decision-making. The evidence on warehouse floors shows a narrower but deeper automation footprint than public discourse suggests, with robots and humans operating in specialized but complementary roles.
What to Watch Next Week
-
Port Congestion Timeline Updates: Monitor for revised congestion forecasts from major Asia terminals (Shanghai, Singapore, Hong Kong) as October peak season demand materializes and shipping lines announce sailing schedule adjustments.
-
Container Rate Movement: Watch Drewry World Container Index and spot rate indicators for direction shifts as Asian port capacity pressures either ease or intensify—critical signals for Q4 procurement decisions.
-
Red Sea/Alternative Route Pricing: Track whether Cape of Good Hope diversions stabilize at the 15-25% premium or compress as more capacity diverts, signaling potential cost relief for Europe-bound cargo.
-
Supply Chain Financing Expansion: Observe announcements from logistics providers offering enhanced financing, compliance, and warehousing services as value migration away from pure brokerage accelerates in response to volatility.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
