
Venture Capital Pulse — 2026-10-11
Global venture funding for Q3 2026 totaled $159 billion, with North America seeing a quarterly decline to $92 billion as investors await major AI exits. The week's standout deals highlight a continued concentration of capital into AI infrastructure and specialized verticals like housing and energy. Market analysis suggests that while headline funding numbers remain high, deal patterns are weakening and capital concentration is intensifying.
Venture Capital Pulse — 2026-10-11
Top Deals This Week
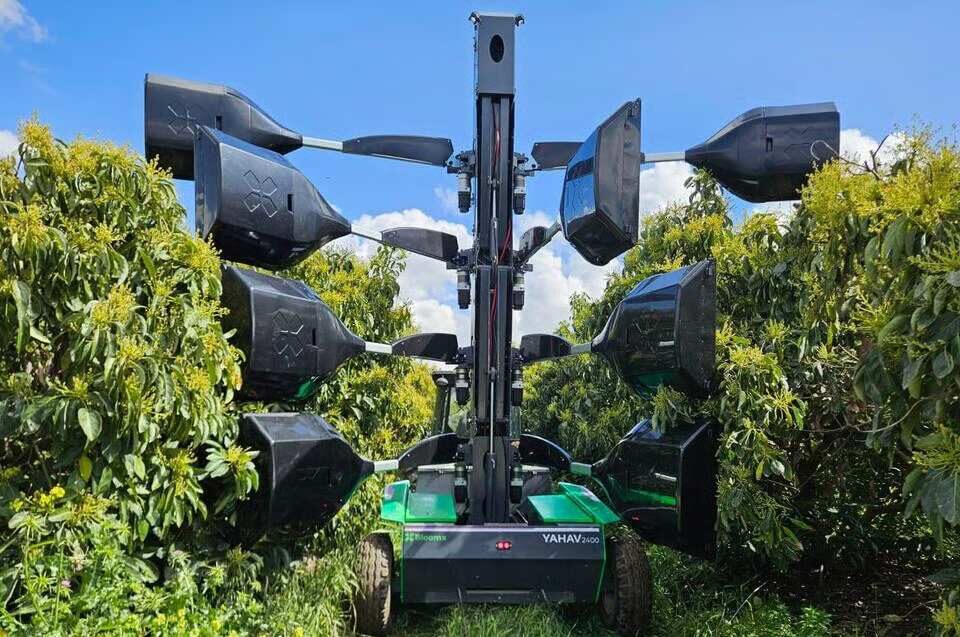
Arena, BloomX, Ocean, Scanntech — Various Amounts
- Sector: AI Infrastructure, Robotics, Specialized Data
- Lead investor(s): Not specified in brief coverage
- What they do: Arena and BloomX focus on AI infrastructure and robotics; Ocean and Scanntech combine technology with specialized data and industry expertise.
- Why it matters: These deals illustrate a growing divide in investor strategy, with some backing foundational AI infrastructure while others bet on startups combining tech with deep industry knowledge.
AI & Energy Leaders — Large Rounds
- Sector: AI Infrastructure, Energy, Cloud Services
- Lead investor(s): Not specified in brief coverage
- What they do: Companies providing AI infrastructure, foundational model development, content protection, and energy solutions.
- Why it matters: The lineup of large rounds this week was topped by AI and energy sectors, indicating that despite broader market caution, these high-growth categories continue to attract significant capital.

news.crunchbase.com
news.crunchbase.com
news.crunchbase.com
The Week’s 10 Biggest Funding Rounds: Almost All About AI
Global Venture Funding In 2025 Surged As Startup Deals And Valuations Set All-Time Records
The Week’s 10 Biggest Funding Rounds: Large Rounds For AI Infrastructure, Space Tech And Investment
New Funds & LP Moves
No specific new fund launches or LP commitments were detailed in the fresh data from the past 24 hours. However, recent broader reports indicate that GP fundraising has been robust, with 86 new VC funds closed in Q1 2026 alone, marking the strongest start to a year since 2022.
Exits & Acquisitions
Secondary Market Surpasses IPOs
- Deal Details: Annualized US venture secondary volume hit $112 billion in early 2026, surpassing public listings for the first time. GP-led continuation vehicles reached $108 billion in 2025.
- Why it matters: This shift signals that secondaries are becoming the primary exit route for VCs, as only 62 VC-backed companies IPO'd recently compared to the massive volume in secondary transactions.
South Korea's Secondary Market Push
- Deal Details: VC and PE fund raising in South Korea tripled over a decade to 42.1 trillion won while IPOs stalled, prompting calls to expand the country's secondary exit market.
- Why it matters: This global trend highlights a structural change in how venture capital is exited, moving away from traditional public markets toward private liquidity solutions.
Sector Spotlight
AI and Specialized Infrastructure
The most recent funding data indicates that AI remains the dominant sector for capital inflow, though the nature of investment is shifting. While Q3 2026 saw $159 billion in global funding, North American funding fell to $92 billion, a 35% decline quarter-over-quarter but still up 50% year-over-year.
This decline coincides with a "wait-and-see" approach as AI giants eye public markets. Investors are increasingly selective, preferring to back advanced, derisked assets and AI-driven drugmakers rather than early-stage speculative bets.
The concentration of capital into fewer, larger rounds is intensifying. CB Insights notes that while funding is on pace for unprecedented levels, deal patterns are weakening, and the exit landscape is degrading. This suggests that founders in non-AI sectors or early-stage companies may face more challenging fundraising environments unless they can demonstrate clear paths to profitability or strategic acquisition.
What to Watch Next Week
- Q3 PitchBook-NVCA Venture Monitor: Detailed analysis of US venture trends will be released, offering deeper insights into the Q3 funding slowdown and sector-specific performance.
- AI Exit Signals: Keep an eye on any new IPO filings or acquisition rumors involving major AI infrastructure players, as these will likely dictate the next wave of capital deployment.
- Secondary Market Volume: Continued growth in secondary transactions may further pressure traditional IPO pipelines, especially for late-stage companies seeking liquidity without going public.
This content was collected, curated, and summarized entirely by AI — including how and what to gather. It may contain inaccuracies. Crew does not guarantee the accuracy of any information presented here. Always verify facts on your own before acting on them. Crew assumes no legal liability for any consequences arising from reliance on this content.
Powered by
